PART 1
My daughter-in-law told me to “stay out of our finances” after months of relying on an emergency fund, a credit card, and money intended for a house deposit that were all still tied to my name. My son sat beside her at my kitchen island and barely spoke while she explained that I had no business asking where the money was going. I didn’t argue with her. I didn’t list all the times I had quietly stepped in to help them.
I simply closed the folder lying in front of me, walked them to the door, and made one phone call after their car vanished down the street. The next morning, she went to the bank expecting everything to function exactly as it always had.
It didn’t.
For years, I had convinced myself that helping my son was simply part of being family.
When daycare became too expensive, I paid a portion of it.
When their car needed a major repair during the winter, I covered the cost.
When groceries, school clothes, or some unexpected bill stretched their budget too far, they had access to an emergency account.
I never kept track of what I gave them.
After my husband died, though, I became especially careful about one thing: protecting the money we had put aside for our grandchildren.
He had spent his whole career reading every line of every document before signing his name.
“Paper remembers,” he used to tell me.
I understood exactly what he meant the night my son and daughter-in-law came over after Thanksgiving.
The serving dishes had finally been put away. One of the children’s crayons was still lying under a barstool.
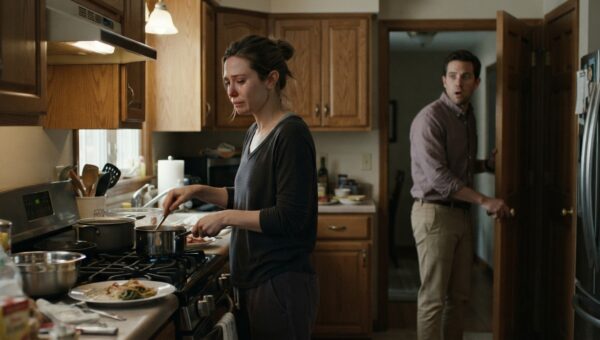
My coffee had gone cold beside me when my daughter-in-law placed a glossy real-estate folder on the kitchen island.
“We found the house,” she said.
It was a beautiful property in Worthington.
Good schools.
A large backyard.
A renovated kitchen.
The asking price was $890,000.
I looked at my son.
“That’s quite a bit more than you were planning to spend.”
He lowered his eyes.
His wife answered instead.
“We can afford the monthly payments.”
“Then what exactly do you need from me?”
She opened the folder to a page covered in highlighted figures.
“The down payment.”
I studied the numbers.
Their own savings were listed.
So was an amount they expected to take from a family account.
Then I saw another figure.
One I recognized immediately.
It came from money that had been set aside for the children’s future.
I closed the folder.
“No.”
She stared at me.
“You haven’t even heard the whole plan.”
“I’ve heard enough to know what you’re asking.”
“That money would benefit the children.”
“It will,” I said. “When it’s actually used for them.”
My son shifted slightly in his chair.
His wife folded her hands carefully on the countertop.
Then her tone changed.
Quieter.
Colder.
“We’re tired of having every financial decision questioned.”
I looked at the credit card sitting beside my son’s wallet.
Then at the mortgage paperwork.
Then back at her.
“If you want your finances completely independent from mine, I respect that.”
She gave a small nod.
“Good.”
“But you can’t tell me to stay out while continuing to build your plans around accounts that are still connected to me.”
The kitchen became silent.
My son rubbed his thumb along the edge of his phone.
His wife’s expression hardened.
“Stay out of our finances.”
My son finally said something.
“Mom, please.”
That was the moment something shifted inside me.
Not because she had shouted.
She hadn’t.
Not because my son had said anything particularly cruel.
He hadn’t.
It was everything surrounding those words.
For months, I had been noticing smaller changes.
Phone calls were getting shorter.
Visits required more advance notice.
In family photographs, I somehow never seemed to be standing anywhere near the camera.
My daughter had seen it before I did.
A few weeks earlier, she had been sitting at that same kitchen island when she asked me one simple question.
“When was the last time he came here by himself?”
I couldn’t answer her.
Now my son was sitting six feet away from me while his wife told me not to ask questions about money that still had my name attached to it.
I stood.
“All right.”
My daughter-in-law looked surprised.
“That’s it?”
“That’s it.”
I walked them outside.
My grandson hugged me and reminded me about the squash soup I had promised to make.
My granddaughter was half asleep against my son’s shoulder while he strapped her into the back seat.
For one second, I almost called him back.
Instead, I stood there and watched their taillights disappear at the end of the quiet suburban street.
Then I went back inside.
The house felt strangely silent.
I opened the estate folder my attorney had prepared several months earlier.
Account records.
Authorization documents.
Copies of signatures.
A yellow note was attached inside the front cover.
Call before changing access.
I stared at it for a long moment.
Then I picked up my phone.
The following morning, I called Victor, the financial adviser who had worked with my husband and me for nearly twenty years.
I had barely finished explaining the situation when he interrupted me.
“Edith, before we change anything, there’s something you need to know.”
My hand tightened around my coffee mug.
“What?”
He hesitated.
“Your daughter-in-law contacted this office.”
I sat straighter.
“When?”
“About three weeks ago.”
Three weeks.
Before Thanksgiving.
Before she placed that house folder on my kitchen island.
Before she ordered me to stay out of their finances.
Victor explained that she had asked specific questions about how access to certain accounts could be changed and what documentation would be required if the person currently responsible for approving changes could no longer do so personally.
Nothing had been changed.
But every question had been recorded.
By midmorning, I was sitting inside a small office near the bank lobby with my estate folder closed across my knees.
At 10:32, the glass doors opened.
My daughter-in-law walked in carrying the same leather tote she had brought to Thanksgiving dinner.
She approached the counter with the easy confidence of someone expecting a routine transaction.
The employee typed for several seconds.
Then stopped.
My daughter-in-law said something I couldn’t hear.
The employee looked at the computer screen again and called for the branch manager.
About a minute later, the manager came out.
“This should be simple,” my daughter-in-law said.
The manager pulled a chair away from the desk.
“Please have a seat.”
Her smile disappeared.
PART 2
I watched through the glass partition as the branch manager pulled up the records on his monitor.
My daughter-in-law took an envelope from her purse. She held it with two hands, resting it on the edge of the wood desk, waiting for him to finish reading whatever was on his screen.
He didn’t take the envelope.
He spoke quietly. His hands stayed flat on the blotter.
I couldn’t hear the words through the double-paned glass, but I watched her shoulders lift. She leaned forward, tapping the glossy leather of her bag, her mouth moving in quick, sharp bursts. The easy smile she had walked in with was completely gone.
She reached for the envelope, pulled out a cashier’s check request form, and slid it toward him.
The manager barely glanced at it. He shook his head once, pushed the paper back across the wood, and picked up his phone.
A second later, the desk phone beside me in the consultant’s office buzzed.
Victor’s assistant answered, listened for five seconds, and looked over at me.
“Edith,” she said quietly. “Mr. Henderson from retail services says Mrs. Miller is asking to withdraw sixty-five thousand dollars from the family reserve line. He needs to know if you’re ready to step in, or if you want him to handle the denial privately.”
I set my hands on the folder in my lap.
For three years, I had treated that account like a safety net for my son’s family. When they moved back to Ohio, my husband and I had opened it so they wouldn’t struggle while getting established. My name was primary. My son was an authorized signer. His wife had never been added to the master agreement, but over time, we had let her handle smaller transfers for convenience.
She had convinced herself convenience was ownership.
“Tell Mr. Henderson I’ll come over,” I said.
I stood, smoothed the front of my wool coat, and walked out of the private office.
The lobby smelled of rain and carpet cleaner. A couple was waiting by the loan brochures near the entrance. When the manager’s office door clicked open, my daughter-in-law turned, expecting an assistant with paperwork.
She saw me instead.
The color left her cheeks in an instant. Her jaw tightened, and she looked from me to the manager’s desk, trying to figure out how long I had been sitting fifty feet away from her.
“Edith,” she said, her voice dropping down to a hiss. “What are you doing here?”
“I bank here, Claire,” I said.
“This is personal business.”
“Not when you’re attempting to draw sixty-five thousand dollars against my signature,” I told her.
The manager stood and offered me the open chair beside her. I didn’t sit. I stayed on my feet, looking down at the cashier’s check request sitting between her manicured nails.
“The earnest money deposit is due by noon,” Claire said, looking at the manager instead of me. “The purchase contract for the Worthington property was accepted yesterday evening. If this draft doesn’t go through, we lose the house and our initial deposit.”
“You put down an offer without having the funds in your own account?” I asked.
“Mark told me the reserve was available,” she snapped. “He said it had always been there for family housing.”
“Mark knew that line required my written authorization for anything over five thousand dollars,” I said. “He knows that because he helped me review the terms after his father passed.”
Claire turned on me then, her eyes hard.
“He’s thirty-four years old, Edith. You treat him like a child. You hold this money over our heads to keep us coming to Sunday dinners and asking your permission for every single step we take. We are trying to build an actual future for your grandchildren, and you’re standing in a bank lobby trying to embarrass me.”
“I am not embarrassing you,” I said evenly. “You came here three weeks ago, Claire. You asked Victor what paperwork was needed if the primary account holder could no longer approve changes personally.”
Her throat moved as she swallowed.
“I asked a general question about estate planning.”
“You asked about incapacitation,” I said. “Victor wrote down the date, the time, and the exact terms you used. You wanted to know if a power of attorney executed by my son could override my signature on the family trusts.”
The manager looked down at his desk blotter.
Claire didn’t answer. Her hand trembled slightly as she pulled the cashier’s check slip back toward herself and shoved it into her tote.
“Where is Mark?” I asked.
She looked away, toward the rainy street beyond the plate glass.
“He’s at the title office,” she said. “Waiting for the wire confirmation.”
PART 3
I didn’t let her call him first.
I walked back to Victor’s office, took my coat off, and sat down at the conference table. I had Victor dial my son’s cell phone on the speaker.
Mark picked up on the second ring. His voice was breathless, full of the hurried energy he always had when he thought a deal was closing.
“Claire? Did they process the draft? The closing agent is asking for the routing number right now.”
“It’s your mother, Mark,” I said.
The line went dead silent.
“Mom?” he said after a long pause. “Where’s Claire?”
“She’s in the lobby,” I said. “And the draft isn’t happening.”
“Mom, please don’t do this,” he pleaded. The sudden panic in his voice made him sound twenty years younger, like the boy who used to break something in the garage and hide behind the side door until dinner. “We have to have that earnest money by twelve o’clock or the sellers walk. We already gave notice on the rental. The kids have already picked out their rooms.”
“You put an offer on an eight-hundred-and-ninety-thousand-dollar home knowing you didn’t have the cash for the deposit,” I said.
“You told us the reserve was for our future.”
“It was for emergencies, Mark. It was for medical bills, or if you lost your contract, or if something happened to the roof over the children’s heads. It was never a private fund for you to buy an estate you cannot afford to maintain.”
“We can make the payments,” he said, his voice rising. “I have the promotion coming in January. Claire has her consulting clients. We ran the numbers.”
“Then show me the numbers,” I said.
He hesitated.
“Mom, the title agent is standing right outside the door.”
“Then bring the folder here,” I told him. “Right now. If you want me to even consider co-signing or releasing a single penny from your father’s trust, you bring the actual mortgage file to this desk.”
He arrived twenty-two minutes later. His tie was loose, his rain jacket was soaked through at the shoulders, and he had three separate manila files crushed under his arm. Claire was already waiting in the hallway outside Victor’s office. When she saw him, she started talking in a frantic whisper, but Mark walked right past her and came through the door.
He dropped the files onto the mahogany table.
“Look at them,” he said, breathing hard. “Look at whatever you want. Just release the wire so we don’t lose the earnest deposit.”
Victor sat beside me and opened the top file.
It didn’t take twenty minutes to see the reality. It took less than three.
The pre-approval letter wasn’t from the primary bank. It was from a secondary mortgage lender, conditional upon an immediate sixty-five thousand dollar cash injection and the payoff of two substantial balances.
One was a personal loan for twenty-two thousand dollars taken out eighteen months earlier.
The other was the retail credit card tied to the joint account my husband and I had set up.
The balance on that card wasn’t the three or four hundred dollars Mark usually mentioned when he asked me to cover the statement.
It was thirty-one thousand four hundred dollars.
Victor pointed his pen at the secondary debt schedule.
“Mark,” Victor said gently. “Your debt-to-income ratio on this application is fifty-two percent. That’s before calculating the new property tax in Worthington.”
I looked up at my son.
“Where did thirty-one thousand dollars go?”
He wouldn’t meet my eyes. He looked at the window, at the gray Ohio rain hitting the glass, at the leather portfolio Claire had carried in behind him.
“We had expenses,” he mumbled.
“You took three trips to Scottsdale this year,” I said, remembering the photos on Claire’s social media that my daughter had shown me. “You leased two new vehicles. You bought a boat slip at the reservoir.”
“We were keeping up appearances for Claire’s firm,” Mark said, his voice cracking. “She needed clients to see that she was established. It was an investment.”
Claire stepped inside the doorway.
“It was our business,” she said coldly. “And we had a plan to pay it down once the home equity came through.”
“What home equity?” I asked, turning to her. “You don’t own the home. You’re trying to buy it with my late husband’s life insurance proceeds while telling me I have no right to look at the paperwork.”
“That money was left for the family,” she said.
“It was left to me,” I replied. “To ensure I never have to burden my children in my old age, and to make sure your children have college educations that don’t bury them in debt. It was never intended to finance an eighty-thousand-dollar kitchen renovation in a house you can’t afford.”
I pulled the estate documents toward me.
I looked at Mark.
“Yesterday you stood in my kitchen and let your wife tell me to stay out of your finances. You agreed with her.”
“I was trying to keep the peace, Mom,” he whispered.
“No,” I said. “You were trying to get my money without answering for your choices. There’s a difference.”
I picked up the pen Victor handed me.
I signed the revocation order on the family reserve account, removing Mark as an authorized user. I signed the form canceling the secondary card. Then I signed the directive transferring the grandchildren’s college funds into an irrevocable trust with Victor as the sole corporate trustee until each child turns twenty-five.
Claire gasped.
“You can’t do that. That ruins the application.”
“The application was already dead, Claire,” Victor said calmly. “No regulated lender would fund this loan once these liabilities were cross-referenced against the true source of the down payment.”
Mark slumped into the chair across from me. He put his face in his hands.
“Mom,” he said, his voice muffled against his palms. “What are we supposed to do?”
“You’re going to stay in your rental,” I told him. “And you’re going to live on what you actually earn.”
ENDING
They lost the house in Worthington that afternoon.
The sellers kept the three-thousand-dollar initial earnest money they had put down from their personal checking account, and the purchase agreement expired at five o’clock.
For the first two months, there was almost total silence.
Mark called once the following week, angry and defensive, repeating things Claire had clearly coached him to say about boundaries and control. I listened without raising my voice. When he paused, waiting for me to apologize or offer a compromise, I simply told him I loved him, but that the accounts remained closed.
He hung up on me.
My daughter came over the following Sunday with groceries. We sat at the kitchen island, the same place where that glossy real-estate folder had been dropped, and ate the squash soup I had promised the children.
“Did you think you were being too hard on them?” she asked me gently.
“I thought about it every night for two weeks,” I told her. “Then I looked at the statements your father kept in that drawer for thirty years. He never gave someone an inch of credit they hadn’t earned, because he knew debt makes people dishonest. I was enabling them to lie to themselves.”
By late winter, the reality had settled in.
Claire’s firm didn’t pick up the high-end corporate accounts she had projected. In February, they turned in the leased SUV and bought a five-year-old sedan with eighty thousand miles on it. Mark took on additional project management hours at his engineering firm to start chipping away at the thirty-one thousand dollars on that credit card.
They didn’t come to Christmas dinner.
It was the first Christmas in my entire life that I spent without my son. I set two wrapped boxes for the children near the tree and left them there until the second week of January.
Then, on a cold Tuesday in late February, my doorbell rang at four in the afternoon.
I opened the door expecting a package delivery.
Mark was standing on the porch alone. His ears were red from the wind, and he had his hands shoved deep into the pockets of an old fleece jacket he hadn’t worn since college.
“Can I come in?” he asked.
I stepped back and held the door open.
He walked into the kitchen, stood beside the counter, and didn’t sit down. He took a single folded sheet of paper from his pocket and laid it next to my coffee mug.
It was a printout from a debt-management counselor in Columbus.
“We enrolled last week,” he said. He didn’t look angry anymore. He just looked tired, the way his father used to look after a sixty-hour week at the plant. “We’re paying seven hundred dollars a month toward the card. The boat slip is gone. Claire took a part-time position with a marketing agency in Dublin to cover the difference.”
I looked at the sheet. His handwriting was at the bottom, listing three monthly payment targets.
“Why are you showing me this?” I asked.
“Because you were right,” he said. The words came hard, scraping out of him like gravel. “I let things get out of hand. I thought if I just kept moving the numbers around, it would all work out before anyone noticed. I let Claire blame you because it was easier than telling her we were drowning.”
I didn’t hug him right away. I didn’t tell him everything was fine, because it wasn’t.
“Your father’s money is safe, Mark,” I said quietly. “And your children’s tuition is safe. That hasn’t changed.”
“I know,” he said.
He stayed for forty-five minutes. We didn’t talk about the Worthington house, and we didn’t talk about Claire’s visit to Victor’s office. We talked about his son’s hockey team and the leak in my utility room ceiling.
Before he left, he picked up the crayon that had been lying under the barstool since Thanksgiving. He rolled it between his fingers for a second, then set it carefully on the notepad by the phone.
“Can we bring them over on Sunday?” he asked.
“Only if you’re coming because you want to be here,” I told him.
He looked at me for a long beat, his eyes clear for the first time in over a year.
“We want to be here, Mom.”
I locked the door behind him after his sedan pulled out onto the quiet street.
The house was still empty, and the bank folders were still tucked away in the office safe where they belonged. But as I washed my coffee cup in the sink, the silence didn’t feel heavy anymore. It just felt like peace.